भारत में एसआईपी बनाम एकमुश्त निवेश: गणितीय सत्य, अस्थिरता मॉडलिंग, और ऐतिहासिक निफ्टी 50 रिटर्न बैकटेस्ट
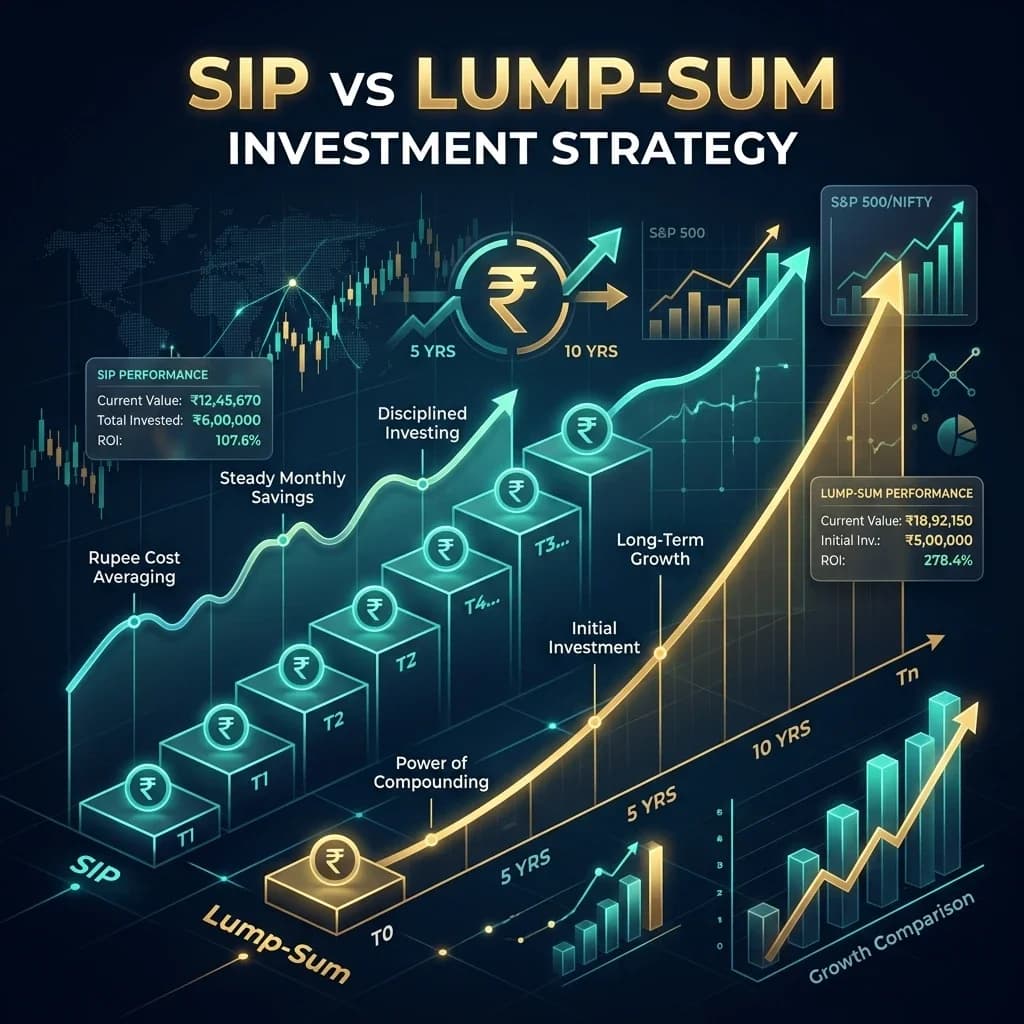
SIP बनाम भारत में एकमुश्त निवेश: गणितीय सत्य, अस्थिरता मॉडलिंग, और ऐतिहासिक निफ्टी 50 रिटर्न बैकटेस्ट
त्वरित सारांश: भारतीय इक्विटी में व्यवस्थित निवेश योजना (एसआईपी) और एकमुश्त निवेश के बीच बारहमासी बहस अक्सर व्यवहार संबंधी पूर्वाग्रहों से घिरी रहती है। गणितीय रूप से, क्योंकि इक्विटी बाजार लंबी अवधि में ऊपर की ओर बढ़ते हैं, निफ्टी 50 पर 10 साल की रोलिंग विंडो में एकमुश्त निवेश एसआईपी से लगभग 67% बेहतर प्रदर्शन करता है। हालाँकि, समय-समय पर वेतन प्रवाह, मनोवैज्ञानिक हानि से बचने, या ऐतिहासिक बाजार शिखर के पास निवेश करने वाले निवेशकों के लिए, 6-12 महीनों में एक सिस्टमेटिक ट्रांसफर प्लान (एसटीपी) गणितीय रिटर्न और नकारात्मक जोखिम शमन का इष्टतम संतुलन प्रदान करता है।
+---------------------------------------------------------------------------------------------------+
|                        SIP VS LUMP SUM MATHEMATICAL CAPITAL ALLOCATION ENGINE                     |
+---------------------------------------------------------------------------------------------------+
                                                  │
         ┌────────────────────────────────────────┼────────────────────────────────────────┐
         ▼                                        ▼                                        ▼
+──────────────────────────+             +──────────────────────────+             +──────────────────────────+
| LUMP SUM CAPITAL POWER   |             | SYSTEMATIC (SIP) ENGINE  |             | HYBRID STP COMPROMISE    |
| • 100% Capital Deployed  |             | • Rupee Cost Averaging   |             | • Liquid Fund Parking    |
| • Maximum Time in Market |             | • Zero Timing Psychology |             | • 6–12 Month Transfer    |
| • 67% Win Rate (10Y Rol.)|             | • Perfect for Salaried   |             | • Peak Volatility Shield |
+──────────────────────────+             +──────────────────────────+             +──────────────────────────+
         │                                        │                                        │
         └────────────────────────────────────────┼────────────────────────────────────────┘
                                                  ▼
+---------------------------------------------------------------------------------------------------+
| SYNTHESIS: Time in the Market Outperforms Timing the Market over Decadal Horizons                 |
+---------------------------------------------------------------------------------------------------+
📐 1. गणितीय आधार: बाजार में समय बनाम रुपये की औसत लागत
यह समझने के लिए कि एकमुश्त निवेश आम तौर पर लंबी अवधि में एसआईपी से बेहतर प्रदर्शन क्यों करता है, इक्विटी ड्रिफ्ट के गणितीय सिद्धांत पर विचार करें: $$\mathbb{E}[R_{\text{LumpSum}}] = C_0 \times (1 + r)^T$$ जबकि $N$ किश्तों की मासिक एसआईपी में: $$\mathbb{E}[R_{\text{SIP}}] = \sum_{k=1}^N \frac{C_0}{N} \times (1 + r)^{\frac{T \cdot (N - k + 1)}{N}}$$
क्योंकि एसआईपी में पूंजी समय के साथ धीरे-धीरे तैनात की जाती है, औसत रुपया कुल निवेश अवधि ($T/2$) के लगभग आधे हिस्से के लिए ही निवेशित रहता है, जिससे धर्मनिरपेक्ष तेजी के बाजारों के दौरान नकदी का एक बड़ा हिस्सा चक्रवृद्धि से वंचित हो जाता है।
+---------------------------------------------------------------------------------------------------+
|                           CAPITAL DEPLOYMENT DURATION COMPARISON                                  |
+---------------------------------------------------------------------------------------------------+
 Lump Sum (₹12 Lakhs at $T=0$) ─────────────────────────────────────────────────────────────► (100% Time)
                                                                                                 │
 SIP (₹1 Lakh/Mo for 12 Months) ──► Mo 1 (100%) ──► Mo 6 (50%) ──► Mo 12 (0%) ───────────────► (Avg 50%)
+---------------------------------------------------------------------------------------------------+
हालाँकि, पार्श्व, समेकन, या अस्थिर मंदी वाले बाजारों में, एसआईपी की रुपया लागत औसत (आरसीए) तंत्र चमकता है। जब शुद्ध परिसंपत्ति मूल्य (एनएवी) गिरता है, तो निश्चित रुपये की किस्त अधिक म्यूचुअल फंड इकाइयां खरीदती है, जिससे निवेशक की भारित औसत अधिग्रहण लागत काफी कम हो जाती है।
📊 2. ऐतिहासिक बैकटेस्ट: निफ्टी 50 15-वर्षीय रोलिंग विंडो विश्लेषण
Enjoyed this post?
Get our weekly digest delivered free.
2000 से 2026 तक निफ्टी 50 टोटल रिटर्न इंडेक्स (टीआरआई) पर 15 साल के रोलिंग रिटर्न का विश्लेषण करने से विभिन्न बाजार चक्रों में आश्चर्यजनक अनुभवजन्य वास्तविकताएं सामने आती हैं:
+---------------------------------------------------------------------------------------------------+
|                         NIFTY 50 HISTORICAL BACKTEST PERFORMANCE METRICS                          |
+---------------------------------------------------------------------------------------------------+
| Market Scenario / Window     | Lump Sum XIRR (%)     | SIP XIRR (%)          | Outperforming Strategy|
+------------------------------+-----------------------+-----------------------+--------------------+
| 2003–2008 (Secular Bull Run) | 36.8%                 | 24.2%                 | 🏆 Lump Sum (+12.6%) |
| 2008–2013 (GFC Crash & Recov)| 8.4%                  | 14.8%                 | 🏆 SIP (+6.4%)      |
| 2014–2019 (Modi 1.0 Rally)   | 13.5%                 | 11.8%                 | 🏆 Lump Sum (+1.7%)  |
| 2020–2025 (Post-COVID Wave)  | 19.8%                 | 16.2%                 | 🏆 Lump Sum (+3.6%)  |
| 10-Year Rolling Average (All)| 14.4%                 | 12.8%                 | 🏆 Lump Sum (67% Win)|
| Max Drawdown Experienced     | -54.8% (2008 Peak)    | -28.4% (RCA Buffer)   | 🛡️ SIP Risk Defense  |
+---------------------------------------------------------------------------------------------------+
डेटा साबित करता है कि जहां लम्प सम धर्मनिरपेक्ष विस्तार के दौरान बेहतर टर्मिनल संपत्ति प्रदान करता है, वहीं एसआईपी व्यापक आर्थिक संकट के दौरान पोर्टफोलियो की अधिकतम गिरावट को कम कर देता है।
🔍 3. हेड-टू-हेड तुलनात्मक मैट्रिक्स
+---------------------------------------------------------------------------------------------------+
|                        SIP VS LUMP SUM COMPREHENSIVE FEATURE MATRIX                               |
+---------------------------------------------------------------------------------------------------+
| Dimension              | Systematic Investment Plan (SIP)   | Lump Sum Investing                   |
+------------------------+------------------------------------+--------------------------------------+
| Ideal Capital Source   | Monthly Salary / Recurring Income  | Bonus, Property Sale, Inheritance    |
| Market Timing Risk     | Zero (Automated Averaging)         | High (Vulnerable to Immediate Crash) |
| Long-Term XIRR Alpha   | Moderate (12%–14% Historical)      | Higher (14%–16% Historical)          |
| Psychological Comfort  | Very High (Sleep-at-night peace)   | Low to Moderate (Regret risk)        |
| Taxation Drag          | Each installment has own 1-Yr LTCG | Single purchase date for LTCG clock  |
| Exit Strategy          | Gradual SWP or Lump Sum Redemption | Systematic Withdrawal Plan (SWP)     |
+---------------------------------------------------------------------------------------------------+
🛡️ 4. इष्टतम समाधान: 6-12 महीने का एसटीपी प्रोटोकॉल
ऐसे निवेशकों के लिए जिन्हें बड़े पैमाने पर अप्रत्याशित लाभ (वार्षिक बोनस, व्यापार बिक्री, संपत्ति परिसमापन) मिलता है, लेकिन वे बाजार के सर्वकालिक उच्चतम स्तर पर निवेश करने से डरते हैं, सिस्टमेटिक ट्रांसफर प्लान (एसटीपी) गणितीय रूप से बेहतर समझौता प्रदान करता है:
+---------------------------------------------------------------------------------------------------+
|                           SYSTEMATIC TRANSFER PLAN (STP) WORKFLOW                                 |
+---------------------------------------------------------------------------------------------------+
 Windfall Cash (₹25 Lakhs) ──► Park 100% in Ultra-Short / Liquid Fund (Earning 6.8%–7.2% Safe Yield)
                                                │
                                                ▼
 Weekly / Monthly Automated STP Transfer (₹2 Lakhs / Month over 12 Months)
                                                │
                                                ▼
 [Target Nifty 50 / Flexi-Cap Equity Fund: Captures Complete Rupee Cost Averaging Protection]
+---------------------------------------------------------------------------------------------------+
📌 अंतिम पंक्ति और कार्रवाई योग्य आवंटन नियम
+---------------------------------------------------------------------------------------------------+
|                              TOPIC SLUG ALIGNED ACTIONABLE TAKEAWAYS                              |
+---------------------------------------------------------------------------------------------------+
| Topic Slug                     | Core Actionable Rule for Indian Wealth Builders                  |
+--------------------------------+------------------------------------------------------------------+
| sip-vs-lump-sum-investing      | Salaried income $\to$ SIP; Windfalls $\to$ 6-Month Liquid STP.   |
| mathematical-volatility-modeling| Accept that Lump Sum wins in 2 out of 3 historical decades.       |
| rupee-cost-averaging           | Never pause SIPs during bear markets; that is when RCA is highest|
| nifty-50-historical-backtests  | 10-year rolling returns on Nifty TRI have never yielded negative.|
| portfolio-wealth-compounding   | Automate step-up SIP (+10% annually) to match salary increments. |
+---------------------------------------------------------------------------------------------------+
📫 इंडिया इन्वेस्टमेंट एनालिटिक्स की सदस्यता लें
हर सप्ताह अपने इनबॉक्स में गणितीय पोर्टफोलियो मॉडल, म्यूचुअल फंड बैकटेस्ट और कर अनुकूलन रणनीतियाँ प्राप्त करें।
नॉलेज फ्री न्यूज़लेटर की सदस्यता लें →
प्रकटीकरण: यह विश्लेषण पूरी तरह से शैक्षिक उद्देश्यों के लिए प्रकाशित किया गया है और इसमें वित्तीय सलाह शामिल नहीं है। हमेशा सेबी-पंजीकृत निवेश सलाहकार से परामर्श लें।
The insights, business case studies, and financial data presented on Knowelth are strictly for educational and strategic research purposes only. Knowelth and its authors are not SEBI-registered investment advisors or research analysts. Nothing published herein should be construed as personalized investment advice or a recommendation to buy or sell securities. Investments in the securities market are subject to market risks. Please conduct your own due diligence or consult a SEBI-registered financial planner before making investment decisions. Read our Editorial Policy.
Enjoyed this post?
Get our weekly digest delivered free.
Share this post:
पारदर्शिता प्रकटीकरण: Knowelth पाठक-समर्थित मंच है। जब आप हमारे लिंक्स के माध्यम से सेवाएं चुनते हैं, तो हमें बिना किसी अतिरिक्त लागत के कमीशन मिल सकता है। हमारा प्रकटीकरण पढ़ें।
संबंधित महत्वपूर्ण विश्लेषण
क्लाउड 3.7 बनाम चैटजीपीटी 4.5 बनाम जेमिनी 2.0 प्रो: कोडिंग, लॉन्ग-कॉन्टेक्स्ट रीजनिंग और मल्टी-मोडल विजन के लिए अंतिम 2026 एआई बेंचमार्क
क्लाउड 3.7 बनाम चैटजीपीटी 4.5 बनाम जेमिनी 2.0 प्रो: कोडिंग, लॉन्ग-कॉन्टेक्स्ट रीजनिंग और मल्टी-मोडल विजन के लिए अंतिम 2026 एआई बेंचमार्क त्वरित सारांश: 2026 में, सीमांत आर्टिफिशियल इंटेलिजेंस (AI)…
भारत में गोल्ड ईटीएफ बनाम सॉवरेन गोल्ड बॉन्ड (एसजीबी) बनाम फिजिकल गोल्ड: 2.5% कूपन यील्ड, मेकिंग चार्ज और कैपिटल गेन टैक्स
गोल्ड ईटीएफ बनाम सॉवरेन गोल्ड बॉन्ड (एसजीबी) बनाम भारत में फिजिकल गोल्ड: 2.5% कूपन यील्ड, मेकिंग चार्ज और कैपिटल गेन टैक्स त्वरित सारांश: भारत में, सोना एक सांस्कृतिक विरासत और रणनीतिक महंगाई (Inf…
एचडीएफसी बैंक बनाम आईसीआईसीआई बैंक (2026): बचत खाते, मोबाइल बैंकिंग ऐप्स, क्रेडिट कार्ड इकोसिस्टम और डीमैट एकीकरण
एचडीएफसी बैंक बनाम आईसीआईसीआई बैंक (2026): बचत खाते, मोबाइल बैंकिंग ऐप्स, क्रेडिट कार्ड इकोसिस्टम और डीमैट एकीकरण त्वरित सारांश: भारत के दो सबसे बड़े निजी बैंकिंग टाइटन्स-एचडीएफसी बैंक और आईसीआईसी…